
MARKETS & WEALTH · INFLATION & INVESTING
September 2026 Inflation: Is Your Portfolio Built for Higher Rates?
Consumer inflation reached 3.7%. Producer prices rose 6.3% over the year. Here is how to check whether your money plan depends on borrowing getting cheaper.
Your portfolio might look diversified. Your savings account might pay interest. Your business might still be profitable. Yet all three can have a weak spot you have never written down: what happens if borrowing stays expensive?
September 2026 inflation has handed investors that uncomfortable question. How much of your plan depends on rates coming down?
Maybe you own a business that needs to refinance. Maybe you bought a long-term bond fund expecting lower yields. Maybe your favorite stock needs years of growth before its valuation makes sense.
Different investments. One shared assumption: money gets cheaper soon.
This week's inflation releases are a reason to examine that assumption. You can do that without pretending to know the Fed's next move.
By the end of this article, you will have a way to test your cash, bonds, stocks, and borrowing against three different rate environments. We will work through the numbers using fictional examples, then turn the exercise into a review you can do with your own statements.
Keep one question beside you as you read: Which part of my financial life needs a favorable forecast just to work?
The numbers worth keeping in front of you
3.7%
CONSUMER INFLATION, YEAR OVER YEAR
6.3%
FINAL-DEMAND PRODUCER INFLATION, YEAR OVER YEAR
3.75%–4.00%
FEDERAL FUNDS TARGET RANGE AFTER THE SEPTEMBER 16 DECISION
Sources: BLS Consumer Price Index, BLS Producer Price Index, and the Federal Reserve's September statement. Annual inflation figures are not seasonally adjusted.
A portfolio can own ten different tickers and still depend on one thing: cheaper money.
September 2026 inflation: read past the headline
Consumer prices increased 0.6% in September on a seasonally adjusted basis. Gasoline rose 9.1% and accounted for more than half the monthly increase. Core CPI, which excludes food and energy, increased 0.3% for the month and 2.6% over the year. BLS CPI release
That mix matters. Energy did much of the lifting, while prices outside food and energy also increased. Declaring the entire problem solved if gasoline cools would be premature. Declaring every category is exploding would also miss the evidence.
The producer report added another warning. Final-demand PPI rose 1.3% for the month, seasonally adjusted. Excluding food, energy, and trade services, it increased 0.5%. BLS PPI release
PPI measures prices received by domestic producers. It is useful evidence about business pricing, but it does not give us next month's grocery bill. Companies can absorb pressure in margins, negotiate costs, change products, or try to pass increases through. Customers may resist.
The investment question is which businesses have room to adapt.
How inflation affects your savings: measure the job, not just the balance
An account balance can grow while its buying power falls. That is why comparing interest earned with inflation can be useful, provided you compare the same period and account for taxes and fees. Your personal spending also differs from the national basket: a renter, a frequent driver, and someone with a paid-off home can experience different pressures.
Hypothetical example: the repair fund. Suppose you have $10,000 set aside for a future home repair. It earns an assumed 3% over one year, leaving $10,300 before taxes and fees. The exact repair you planned rises from $10,000 to $10,500, an assumed 5% increase. Your account grew by $300, but the gap between your savings and the bill became $200.
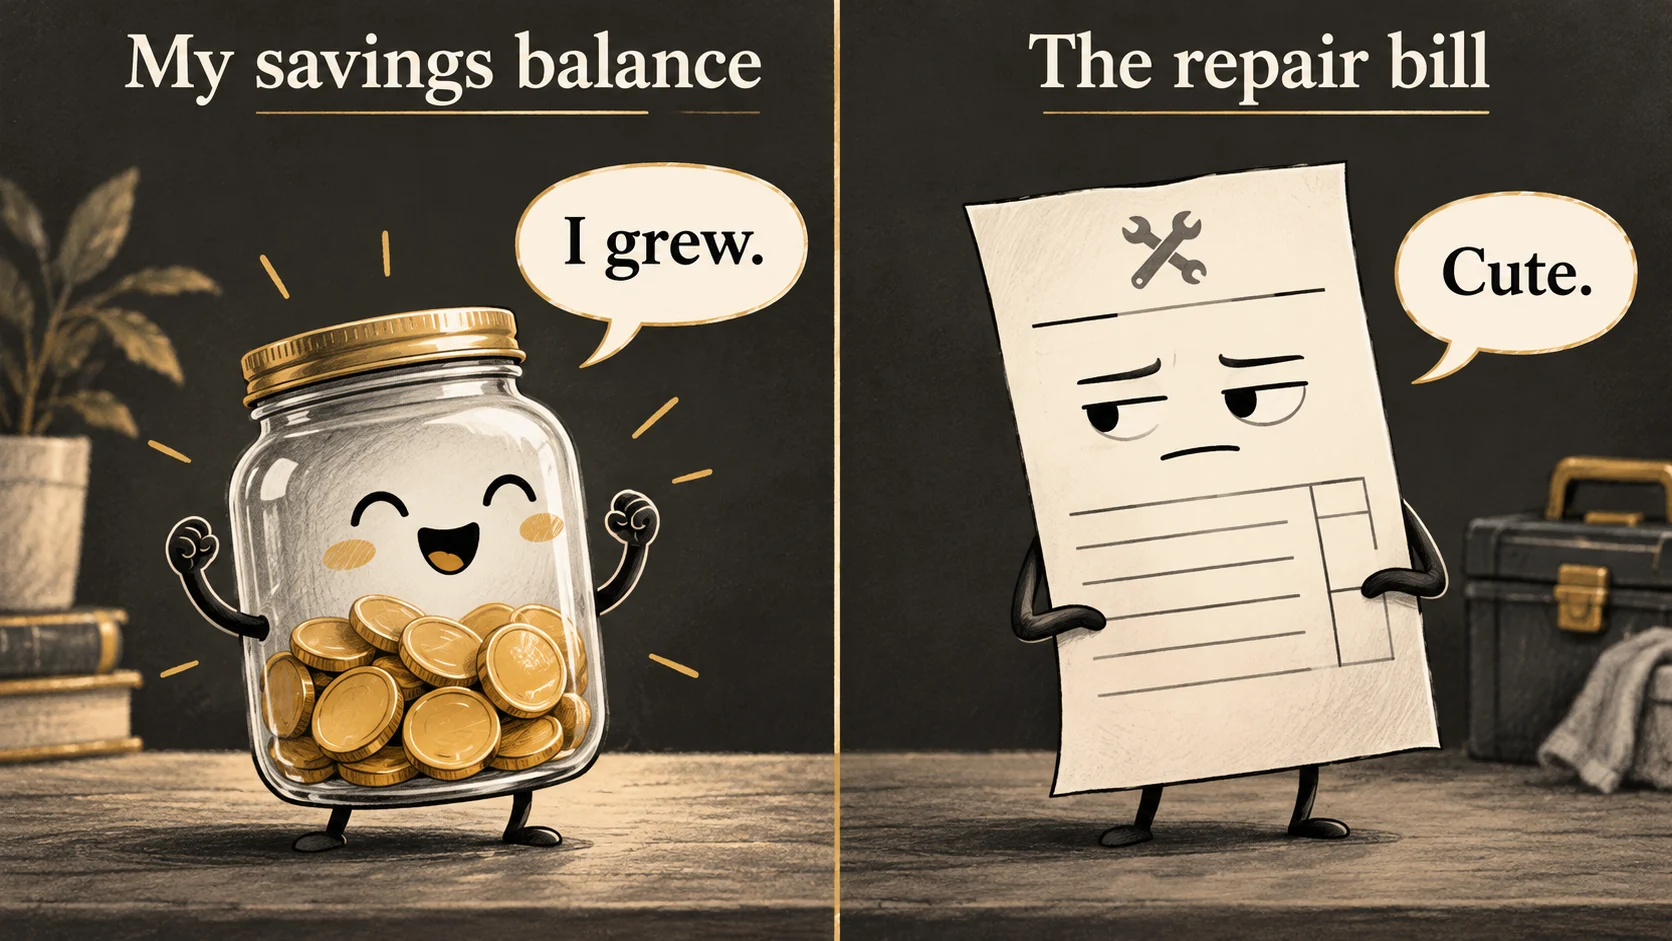
Neither assumed rate is a current savings quote or a forecast. The lesson is about matching money to a purpose. A bigger number on the statement does not necessarily mean you are closer to paying the bill.
That also does not make essential cash a mistake. Money available when the car breaks down serves a different purpose from money invested for retirement. Trying to make every dollar maximize its potential return can leave you selling an investment at a bad time to cover an ordinary expense.
Start with the amount, deadline, and flexibility of each goal. Can the purchase wait? Can its size change? What happens if the investment balance is lower when payment is due?
Build this into your routine: Open MentorSurge's money and credit starting point and choose the cash-flow lesson. Use it to map the timing of income and bills before deciding how much money is genuinely available to invest.
The rate-cut assumption deserves a harder test
On September 16, the Fed raised its target range by a quarter of a percentage point to 3.75%–4.00%. That is a decision already made. Another increase is a possibility to consider, not a fact we can announce in advance. Federal Reserve statement
One important distinction: the Fed's 2% longer-run inflation objective uses the PCE price index. CPI is a separate measure. Comparing the two as if they were identical creates more confidence than clarity. Federal Reserve inflation FAQ
For a useful stress test, write down three scenarios: borrowing stays expensive, it gets more expensive, and it becomes cheaper. Then ask what breaks in each one.
A plan that needs one exact policy outcome deserves closer attention.
Where the pressure can show up
1. The company with a refinancing deadline
Two companies can sell similar products and face very different financial risks. One has cash and long-dated debt. The other needs fresh borrowing while its margins are shrinking.
Read the debt footnote. Look for maturity dates, fixed versus floating rates, and how much operating cash is left after investment spending. Ask whether the business can fund itself if lenders demand tougher terms.
These are research questions, not an automatic instruction to avoid debt. The point is to understand the financing before falling in love with the growth story.
Hypothetical example: a small business refinancing a loan. Imagine a business carries $200,000 of interest-only debt at an assumed 6% annual rate. Annual interest is $12,000. If the whole balance must refinance at an assumed 9%, annual interest becomes $18,000. That is an additional $6,000 a year, or $500 a month, before any new fees.
If the business previously had $30,000 left after operating costs and the old interest bill, that extra interest alone reduces the amount to $24,000, assuming everything else stays unchanged. A three-percentage-point rate increase has consumed 20% of that simplified cash cushion.
This is deliberately simplified: it ignores principal repayments, taxes, loan fees, changing sales, and other cash requirements. It is not a quote or a standard loan structure. Its purpose is to show how financing costs can matter even when customer demand holds up.
An owner should also examine inventory sitting unsold, customers paying late, and required loan conditions. A profitable month on paper does not guarantee cash will arrive before payroll or the lender's due date. For investors, the same question scales up: how dependent is this company on outside funding arriving on favorable terms?
2. The bond fund bought for its yield
A bond's quoted yield does not tell you how much its market price can move. When market interest rates rise, prices of existing fixed-rate bonds generally fall. Longer-maturity bonds usually have greater interest-rate sensitivity than comparable shorter-maturity bonds. Investor.gov bond guidance
Check your fund's duration, credit quality, and role in your plan. Money needed soon deserves special attention. A bond fund can fluctuate even when its holdings continue paying interest.
Also distinguish an individual bond from a fund. An individual bond has contractual payments and a maturity date, subject to the issuer meeting its obligations. A conventional ongoing bond fund holds a changing portfolio; it does not promise to return your purchase price on your personal spending deadline. Selling either before the date you planned can expose you to unfavorable market prices. Investor.gov bond FAQ
The practical question is simple: did you buy the investment to fund a known expense, diversify a long-term portfolio, or speculate on falling yields? Those are different jobs. Be honest about which one you assigned it.
3. The stock that needs everything to go right
A business can grow and still be a disappointing investment at the wrong purchase price.
For each major holding, write a less generous case: slower sales, weaker margins, or a higher financing cost. Would the business still produce cash? Would the valuation still leave room for mistakes?
Treat that as a research exercise. It is more useful than borrowing a stranger's price target and calling it conviction.
Hypothetical example: growth without a higher share price. Consider a fictional company earning $4 per share, valued at 25 times those earnings. That arithmetic gives a $100 share price. Suppose earnings grow 10% to $4.40, but investors subsequently pay only 20 times earnings. The resulting price is $88.
In this illustration, earnings improved while the share price fell 12%. These are invented inputs, not a predicted return or a model of any named stock. They show why a growth thesis needs a valuation assumption. The business result and the price investors will pay for that result are separate moving parts.
For a company you research, write both down. What growth would justify the valuation? What happens if growth is merely good instead of exceptional? The harder a valuation leans on distant success, the more important it becomes to explain the assumptions rather than simply repeat the size of the opportunity.
What happens to stocks and bonds if interest rates stay high?
There is no single outcome for every stock, bond, or household. A useful comparison separates three scenarios and asks where your exposure sits. These are possibilities for planning, not assigned probabilities.
Scenario one: rates stay elevated and the economy keeps growing
Businesses with healthy demand may continue generating cash. Borrowers facing a reset still have to absorb the financing cost. A saver may receive interest, but must evaluate what remains after taxes and changing prices. Long-term investors should avoid assuming that a high policy rate automatically means every company becomes a bad investment.
Research focus: Are sales converting into cash? Are debt costs manageable? Does the investment still make sense at the price paid without a quick rate cut?
Scenario two: inflation stays stubborn and borrowing gets more expensive
Floating-rate borrowers and companies refinancing soon deserve close examination. Existing fixed-rate bonds can face price pressure if market yields rise. Businesses may encounter both higher costs and customers with less flexibility to spend.
Research focus: What can adjust first: expenses, prices, investment spending, or financing? Which changes would damage the business rather than merely delay a project? Identify the pressure points before assuming management can pass every cost to customers.
Scenario three: rates fall while economic demand weakens
Lower borrowing costs can help, but weaker sales or credit losses can offset some of that help. A business waiting for cheaper money may still struggle if its customers stop buying. Bond outcomes also depend on credit quality and the market yields relevant to the securities held, not solely the policy-rate announcement.
Research focus: Can the borrower handle lower revenue? How much demand was essential and how much could be postponed? A rate cut by itself does not answer those questions.
The purpose of this comparison is to uncover dependence. If your explanation for every holding ends with “rates will fall,” you have more research to do.
What to actually do: the 20-minute check
First five minutes: label the money. Which dollars cover upcoming expenses? Which are emergency reserves? Which can genuinely stay invested for years? Time horizon and risk tolerance belong at the center of asset allocation. Investor.gov allocation guidance
Next five: check your own borrowing. List balances, actual interest rates, and any reset dates. Use your statements. A national inflation release cannot tell you what your lender is charging.
Next five: look for repeated exposure. Check whether several funds own the same companies or whether multiple holdings rely on the same favorable economic outcome. Diversification can reduce concentration risk; it cannot eliminate losses. Investor.gov diversification guidance
Final five: write the decision rule. What new evidence would make you revisit a holding? A financing change? Deteriorating cash flow? A position growing beyond your intended allocation? Consider transaction costs and taxes before acting.
You may finish this review and change nothing. That can be a sensible result when the plan still fits.
Turn the review into a one-page record
For each important holding or financial commitment, write five lines: its purpose, when you need the money, the main assumption, the evidence you will check, and the condition that would prompt a review.
For a fictional emergency fund, that might mean covering essential bills, immediate availability, dependable access, checking the account terms, and revisiting the amount after a lasting increase in household expenses. For a researched stock, the evidence might be operating cash flow and upcoming debt maturities. The entries should reflect the actual job rather than a generic label such as “long term.”
Keep the previous version when you update it. That gives you a record of whether your thinking changed because the evidence changed or because the latest headline felt intense. You do not need a complicated spreadsheet. You need an explanation clear enough that you can recognize when it stops being true.
Continue learning: Use MentorSurge's investing and markets starting point and choose the risk-and-time-horizon lesson. Bring your one-page record and compare your holdings with the dates when you actually need the money.
September 2026 inflation and investing: common questions
Does higher inflation mean I should sell all my stocks?
An inflation release alone cannot determine the right allocation for your circumstances. Your time horizon, liquidity needs, concentration, and ability to tolerate losses matter. First identify which assumptions changed. Selling everything creates its own decisions about timing, taxes, and when to reinvest. A disciplined review should explain what problem any proposed trade would solve.
Are bonds safe when interest rates rise?
Safety has several dimensions. An issuer may meet every payment while the bond's market price falls. Credit quality, interest-rate sensitivity, and your need to sell all matter. Match the question to the risk: “Will I get paid?” and “What could I sell this for next month?” are different questions. Investor.gov bond risks
Does a higher PPI number mean consumer inflation will match it?
No. Producer and consumer measures cover different transactions and weights. Businesses may absorb costs, change margins, or adjust prices, and the timing varies. Read the producer report as another piece of evidence about the economy rather than a direct conversion formula for a future consumer number. BLS PPI release
Should I use emergency savings to pay down debt?
That decision depends on the debt's actual cost, your access to cash, upcoming bills, and income reliability. Eliminating a balance while leaving no room for a foreseeable expense can force you to borrow again. Lay out both sides before choosing: the financing cost you may reduce and the liquidity you would give up. Seek qualified guidance when the trade-off is material.
How often should I check my portfolio after an inflation report?
Use a review schedule you can maintain and clear triggers for meaningful changes. A new borrowing deadline, a changed goal, or a material business deterioration can justify attention. Reopening the app after every headline does not automatically improve the decision. Keep a dated record, then check whether the new information actually changes it.
The bottom line
The useful response to an inflation headline is a better understanding of what you own, what you owe, and when you need your money.
Write down the assumptions. Check the weak spots. Give yourself a plan that can survive more than one version of the future.
Take one useful next step: Visit MentorSurge's Start Here guide. Choose money and credit if you need a clearer picture of your bills and borrowing, or investing and markets if you need to match risk to your timeline. Complete one lesson with your own numbers before opening another market headline.
Educational commentary only, not individualized investment, tax, or legal advice. Investing involves risk, including loss of principal. Examples and scenarios are illustrative, not forecasts or recommendations to buy or sell a security. Economic data may be revised.